Business
Neurodivergent Entrepreneurship: Building Businesses That Work With Your Brain

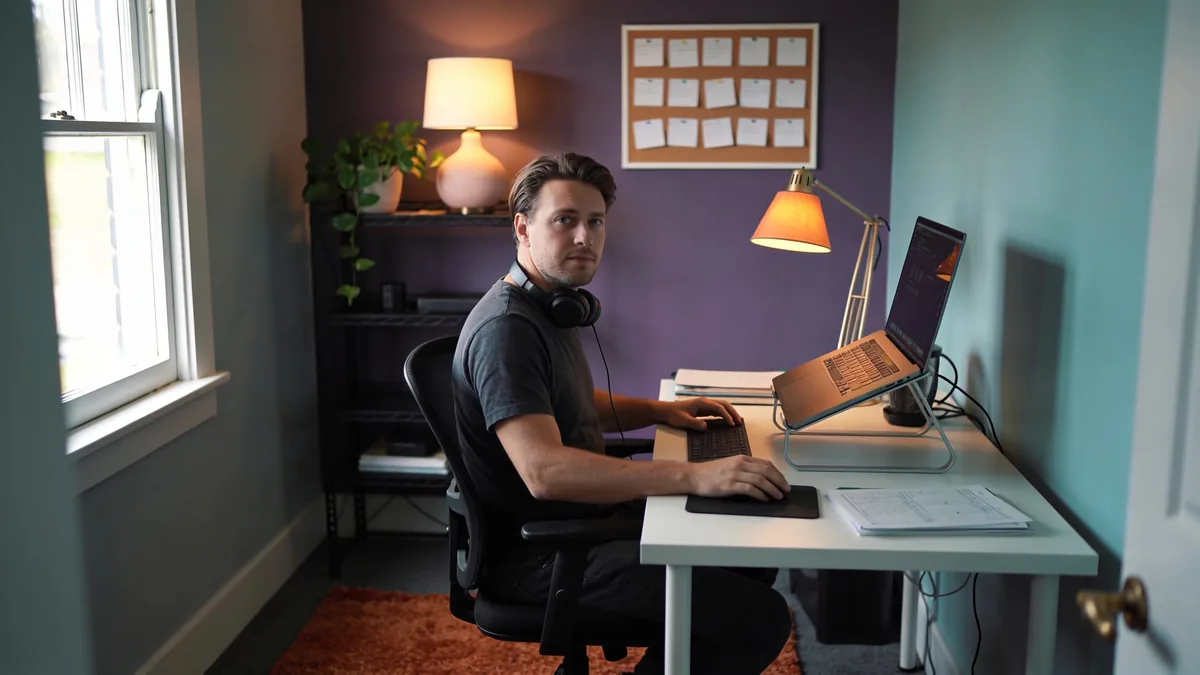
If the standard advice about running a business has never quite fitted the way your mind works, that is not a personal failure. It usually means the advice was written for a different operating system. You have probably already built a set of workarounds to get through the day, and the useful move now is to turn those workarounds into the design of your business rather than treating them as repairs.
What follows is practical rather than medical. It is written for founders who already know how they work, and who want a business that stops fighting it.
Start with how you work
Before designing anything, collect the data. For a fortnight, note when focus arrives and when it leaves, which tasks you avoid until they are urgent, and which hours of the day are reliably good. Do not judge the notes; just take them. Most people have never looked at their own working patterns this closely, and the patterns are usually more consistent than they feel from the inside.
The strengths, named honestly
Three that show up often in conversations with neurodivergent founders: hyperfocus, the ability to go deep on something interesting for longer than most people can bear; pattern recognition, a knack for spotting the inconsistency everyone else has stopped noticing; and resilience, built the hard way by years of environments that were not designed with you in mind.
Name them honestly, which means with the costs attached. Hyperfocus runs on interest, not on schedule, and it can swallow a day whole. Pattern recognition finds problems as fast as it finds solutions. Resilience is real, but it was paid for, and it is not infinite. A strength you understand, including its price, is a strength you can build a week around.
Build systems that carry what you drop
Willpower is the wrong tool for a job like this. Systems are the right one. Put everything that matters into a calendar rather than into memory. Use checklists for anything that repeats. Template the emails and proposals you send most. Set reminders loudly and trust them quietly. The goal is scaffolding, so the parts of running a business that bore you do not depend on the parts that energise you turning up on schedule.
Delegation is a design decision
Every founder thinks they cannot afford help. What they usually mean is that they have not decided what to hand over. Pick the tasks that drain you and cost the least judgement: bookkeeping, scheduling, the inbox, the invoicing. Starting small is not settling. A few hours of someone else’s competence each week is often the difference between a business that runs and one that holds you hostage.
Schedule energy, not just time
A calendar that treats all hours as equal will fail you. Book the demanding work into your best hours and protect them properly. Batch the calls that take a similar kind of effort. Leave real gaps after anything social, and treat recovery as part of the schedule rather than the reward for finishing it. An energy-first week looks softer on paper and produces more of the work that matters.
Work with your environment, and with your team
Ask for the conditions you need, of yourself first: quiet, headphones, written briefs, fewer meetings, a door. When you are the boss, you set those conditions, and it is worth noticing how much of the friction in your week was never necessary. Disclosure stays a choice rather than an obligation. You can design the accommodation without explaining it to anyone.
If you go on to lead a team, the same logic scales, because the conditions that let one person do their best work are rarely the ones the next person needs. Managing a multigenerational workforce is the manager’s version of the same problem, and the founder’s version is to build the conditions into the company from the start.
A business that fits the person running it
The point was never to fix yourself into a conventional founder shape. It is to build something that uses what you are good at, absorbs the parts you are not, and survives a week when the energy is low. Start with one system this month and one thing delegated by the next. That is a slower path than the advice columns sell, and it is the one that is still standing a year from now.
Sources: Neurodiversity Hub (neurodiversityhub.org) publishes resources on neurodiversity in education and employment; Amaze (amaze.org.au) and ADHD Australia (adhdaustralia.org.au) publish Australian information and support.

The question most drivers ask before a holiday trip, “are double demerits on this weekend?”, is in fact two questions. The first is when the doubling applies. The second is to which offences it applies. Neither has a national answer, because there is no single national double demerit scheme in Australia. Each state and territory sets its own road rules, in the same way that the rules for riding an e-scooter differ from one state to the next, and the arrangements for demerit points differ accordingly.
This article sets out the position jurisdiction by jurisdiction, as published by the responsible agency, with the date on which each source was read. It is intended to help a driver identify the rules that apply in the state in which they will be driving over the Christmas and New Year period. It is general information. It does not set out fine amounts, and it is not legal advice.
New South Wales
Transport for NSW, through its Centre for Road Safety, operates double demerit periods attached to public holidays.
- Offences to which the scheme applies. During a double demerit period in New South Wales, the scheme applies to the following offences:
- speeding;
- illegal use of a mobile phone;
- not wearing a seatbelt, or wearing it incorrectly;
- driving with a passenger who is not wearing a seatbelt or an approved restraint; and
- riding a motorcycle without a helmet.
- The Christmas period. The double demerit period for Christmas Day, Boxing Day and New Year’s Day runs from 24 December 2026 to 3 January 2027, according to the Transport for NSW list read on 17 October 2026.
- School zones. Transport for NSW notes that additional penalties may apply to offences committed in school zones on school days that fall within a double demerit period.
The Christmas period is not the only one. Because the New South Wales periods attach to public holidays, Transport for NSW publishes a list of periods across the year, and the list is the document to consult before any long weekend, not only before Christmas.
A driver in New South Wales should therefore treat the offences above as those of concern, and the dates above as the period during which they attract additional points over the Christmas and New Year holidays.
Western Australia
The Road Safety Commission of Western Australia publishes its own arrangements, most recently updated on 4 August 2026.
- Offences to which the scheme applies. During holiday periods and long weekends, double demerits apply in Western Australia to:
- speeding;
- drink or drug driving;
- failing to wear a seatbelt or child restraint correctly;
- running a red light;
- illegal use of a mobile phone; and
- driving in a manner, or with a device, designed to evade a speed camera.
- The speed camera evasion offence. The Road Safety Commission states that this offence attracts 14 points during a double demerit period.
- The Christmas period. The Western Australian period runs from Friday 18 December 2026 to Sunday 3 January 2027, according to the Road Safety Commission page read on 17 October 2026.
Two points of difference from New South Wales deserve attention. The Western Australian list of offences is longer, and includes drink or drug driving and red light offences, which do not appear on the New South Wales list. The Western Australian Christmas period also begins earlier, on 18 December rather than 24 December. A driver who travels between the two states over the holidays should not assume that the rules or dates of one apply in the other.
As in New South Wales, the Christmas period is one of several. The Road Safety Commission applies double demerits during holiday periods and long weekends generally, and its page should be read before each of them.
Queensland: all year, for repeat offences
Queensland operates on a different model. The rule that the Queensland Government describes is not tied to holiday periods. Double demerit points apply all year, to repeat offences.
- The rule. Double points apply to a second or later offence in the same offence group, committed within one year of the previous offence in that group. The rule applies at any time of year.
- The offence groups. The Queensland Government lists the following groups:
- speeding more than 20 km/h over the speed limit;
- mobile phone offences;
- driver seatbelt offences;
- failing to ensure that passengers under 16 are restrained; and
- motorcycle helmet offences.
- The group, not the offence. The second offence need only fall within the same group as the first. It need not be an identical offence.
The practical consequence is that a Queensland driver does not need to check a calendar to know whether the rule applies. The relevant question is whether that driver has committed an offence in the same group within the previous year.
An illustration, drawn only from the rule as the Queensland Government states it, may assist. A driver who is detected speeding at more than 20 km/h over the limit in March, and again at more than 20 km/h over the limit in November of the same year, has committed a second offence in the same group within one year, and double points apply to the November offence. The month of November is irrelevant to that outcome. The same reasoning applies to the other groups: a second mobile phone offence within a year of the first attracts double points whether it occurs in a holiday week or an ordinary one.
The Australian Capital Territory
The Australian Capital Territory also runs double demerit periods over holidays. The dates and the offences to which they apply are published by the territory’s own authorities. A driver who will be in Canberra or elsewhere in the territory over Christmas should confirm the current dates and the offence list with Access Canberra or ACT Policing before travelling. This article does not set them out.
Everywhere else
The remaining states and territories do not appear in the schemes described above. That statement should not be read as a guarantee about any particular jurisdiction. Road rules change, and the authority responsible in each state is the only reliable source for the rules in force on a given date.
The recommended course is straightforward. Before a long drive, a driver should check the road authority of every state or territory through which the route passes, rather than assuming that the rules of the home state apply on the other side of a border.
One further boundary should be stated. This article makes no statement about how demerit points incurred in one state are recorded against a licence issued in another. That question is a matter for the licensing authority that issued the licence, and a driver with a concern about it should put the question to that authority directly.
Practical points for the Christmas drive
The following points apply to drivers planning a trip over the Christmas and New Year period.
- Confirm the dates at the source. The Transport for NSW and Road Safety Commission pages publish the dates of each double demerit period. The Queensland Government page sets out the repeat-offence rule. Each should be read close to the date of travel.
- Mobile phones. Mobile phone offences appear on the New South Wales and Western Australian lists and in a Queensland offence group. Mobile phone detection cameras exist, and a driver should not assume that an offence will go unobserved on a quiet road. The phone should be set up before departure and left alone while driving.
- Seatbelts for every passenger. Seatbelt and restraint offences appear in all three schemes. In New South Wales the scheme extends to driving with a passenger who is not restrained, and in Queensland it extends to passengers under 16. The responsibility therefore rests with the driver as well as the passenger.
- Provisional drivers. Provisional drivers face licence suspension at fewer demerit points than drivers on a full licence. A provisional driver on a holiday trip has less margin than an experienced driver in the same car.
- The vehicle. A long drive in summer places demands on a vehicle that a daily commute does not. The service history, including what logbook servicing does and does not mean for a warranty, is worth reviewing before departure, as is the cooling system, given the conditions on inland highways in December. Thinker has set out ways to keep an engine cool and efficient in hot weather.
- Drink and drug driving in Western Australia. Drink or drug driving appears on the Western Australian list of offences that attract double demerits during a holiday period. A driver attending Christmas or New Year gatherings in that state should arrange the journey home before the gathering begins, not after.
- Rest. The holiday period is also a period of long distances and heat. Planned stops at rest areas break up the drive and give the driver an opportunity to check the route and the conditions ahead.
Check the dates before the drive
The position can be summarised in five clauses.
- There is no national double demerit scheme. Each jurisdiction sets its own rules.
- In New South Wales, the Christmas period runs from 24 December 2026 to 3 January 2027 (Transport for NSW, read 17 October 2026), and the scheme applies to speeding, mobile phone, seatbelt, restraint and motorcycle helmet offences.
- In Western Australia, the Christmas period runs from Friday 18 December 2026 to Sunday 3 January 2027 (Road Safety Commission, read 17 October 2026), and the list of offences is longer, including drink or drug driving and red light offences.
- In Queensland, double points apply all year to a second or later offence in the same group within one year.
- In the Australian Capital Territory, the dates should be confirmed with Access Canberra or ACT Policing, and in every other jurisdiction, with the relevant road authority.
A driver who has confirmed the dates and the offence list for each state on the route has done what the rules require of a careful driver before the trip begins. The remaining obligation is the same in every jurisdiction and in every period: to drive within the rules for the whole of the journey.
Sources: Double demerits, Transport for NSW Centre for Road Safety (https://roadsafety.transport.nsw.gov.au/campaigns/double-demerits.html); Double demerits, Road Safety Commission WA (https://www.wa.gov.au/organisation/road-safety-commission/double-demerits); Double demerit points, Queensland Government (https://www.qld.gov.au/transport/safety/fines/demerit/double)
A taxpayer who lodges an electronic return and waits for the refund is watching two clocks, and only one of them is the clock that matters. The first is the calendar, which counts days as ordinary people count them. The second is the business day count the Australian Taxation Office applies to its published target, and the difference between the two explains most of the anxiety that gathers in the first fortnight after lodgment.
Two figures resolve the greater part of that anxiety before it begins. Most electronically lodged returns are processed within 12 business days, and the ATO will not take an enquiry about a delay until 30 days have passed. Between those two numbers sits the whole of this article: how a return moves, what slows one down, what can and cannot be learned while waiting, and where the taxpayer should look first.
1. The two clocks
The published processing target is expressed in business days, and a business day is not any day on which a taxpayer happens to be waiting. Weekends and public holidays are excluded from the count, which means the 12 business days of the target are closer to two to three weeks of ordinary calendar time. A return lodged on a Friday before a long weekend has already lost ground that has nothing to do with its contents.
The second figure is the service standard for contact, and it is stated with the same precision. The ATO will not take an enquiry about a delay until 30 days have passed since lodgment. A telephone call on day eight does not advance the return and does not open a case; the file is simply not yet at the point the system treats as delayed. Knowing this in advance spares the taxpayer a hold queue and a wasted morning, and it converts the waiting period from a mystery into a timetable.
The business day convention is not arbitrary. It reflects the offices that perform the work, which keep ordinary hours and observe public holidays, and a target expressed in working time is the only honest way to state what the system can do. The practical translation for a taxpayer is to add the weekends and public holidays to whatever figure is quoted, and to expect the greater part of the wait to be quiet rather than eventful.
An example makes the two clocks concrete. A return lodged on a Monday in an ordinary working week begins its 12 business days that day, and the count crosses three weekends and roughly two and a half weeks of the calendar before it completes. The same return lodged on the Thursday before a public holiday has lost a business day before it starts, and nothing about its contents has changed. The acknowledgment the system issues when the return is received records the date from which the count runs, and that date, rather than the date the taxpayer remembers pressing submit, is the one worth keeping.
2. How a return moves
The journey from lodgment to refund has four stages, and each one has a defined purpose. The first is recording: the return is received and entered against the taxpayer’s account, and a lodgment acknowledgment follows. Until this stage completes, nothing else has begun, and the clock has not started.
The second stage is verification, and it is where most time is spent without any fault attaching to the taxpayer. The ATO compares the figures in the return against data supplied by employers, banks, health funds, government agencies and other institutions. Where the figures agree, the stage passes quietly. Where they differ, or where a data provider has not yet supplied its file, the return waits, and no amount of telephoning will summon a third party’s data any faster.
The third stage is processing, in which the return is assessed and any offset or debt is applied. The fourth is issue: the refund is paid to the bank account recorded with the ATO. A return that clears all four stages within the published target is the ordinary case rather than a lucky one, which is worth stating plainly because the ordinary case attracts no discussion anywhere.
It is worth stating what the sequence does not contain. No stage rewards impatience, and no stage is shortened by a telephone call. The verification stage depends on third parties, and the processing stage is automated in the ordinary case. The taxpayer’s role in the sequence is complete at lodgment, which is a useful thing to remember when the first fortnight feels long.
3. The flags that put a return over
When a return runs beyond the target, the cause is usually one of a defined set of circumstances, and each of them is known to the system in advance.
- An amended or re-lodged return. A correction restarts checks that the original lodgment had already cleared.
- Several income years lodged at once. Each year is assessed in sequence rather than in parallel, and the queue is the queue.
- Insolvency administration. Where a practitioner has been appointed, the refund may be dealt with through the administration rather than paid directly.
- Incorrect or stale bank details. A refund cannot be paid to an account that is closed or wrongly recorded, and this flag carries a second consequence described in the next section.
- Verification back-and-forth. Where data mismatches, correspondence may be issued, and the return waits on the taxpayer’s reply.
- An existing tax debt. A refund can be offset against an amount already owed, in which case the refund is not late; it has been applied elsewhere.
Two further timetables apply to returns that leave the electronic path. A return sent to manual processing can take up to 30 calendar days, and a paper return can take up to 50 business days, with up to seven weeks before it appears in the systems at all. Those figures are worth keeping in proportion: they describe the exceptions, and the electronic majority never meets them.
The list is worth reading twice, because its entries divide into two kinds. Amended returns and multiple years lodged at once are consequences of choices made by the taxpayer, and they can be planned around. Insolvency, mismatched data and a person’s own bank details sit in different columns: one is weather, one is a third party’s timetable, and one is a two-minute check that rewards being done early. Sorting a particular situation into those columns tells a taxpayer whether the wait is something to manage or something to endure.
4. The 90-day rule
The least-known provision in this subject concerns bank details rather than tax. Under the Treasury Laws Amendment (2024 Tax and Other Measures No. 1) Act 2024, the ATO may retain a refund for up to 90 days where it does not hold valid Australian bank account details for the taxpayer. The measure is aimed at fraud and error, and its practical effect for an ordinary taxpayer is simple: a refund with nowhere to go sits in the system rather than at the taxpayer’s bank.
The remedy is proportionate to the problem. Account details should be checked and corrected before lodgment, not after a delay has begun, and the check takes a few minutes through the same online services used to lodge. A refund held under this provision is not lost and not in dispute; it is waiting on an instruction that only the taxpayer can give.
The provision also carries a lesson about sequencing. Bank details are checked most easily at the moment a return is prepared, when the account is open on the screen and the taxpayer is already attending to the figures. Left until a delay has begun, the same check has to be made from a standing start, with the refund already marked for retention and the correction waiting its turn behind everything else. The few minutes spent early are the provision’s entire remedy, and its 90 days exist for the cases where nobody spent them.
5. What a refund is
The honest description of a refund is that it is the taxpayer’s own money, returned after having been withheld through the year on the assumption that more would be owed than was. It is not a benefit, a bonus or a reward for lodging, and a large refund is not a piece of good fortune. It is evidence that the withholding through the year was set higher than the year’s actual liability, which is a signal to review the withholding declaration rather than to celebrate.
What the refund is not, and this boundary matters, is a measure of whether enough was claimed. Claiming more is a different question from processing time, and the site treats it separately in its guide to the deductions and offsets people miss. Nor is the refund a reason to engage an agent or to manage without one; when a tax agent earns their fee is a question about complexity, and it is answered on its own terms elsewhere.
Where the large refund repeats year after year, the remedy is procedural rather than heroic. The withholding declaration held by an employer sets the amount deducted through the year, and adjusting it so that take-home pay reflects the eventual liability is how the annual lump sum stops arriving. A taxpayer who prefers the lump sum is making a choice, provided the choice is deliberate rather than the default.
6. What to do while you wait, in order
The actions available to a waiting taxpayer are few, and performing them in order prevents the most common wasted effort.
- Check the return’s status. The ATO app and online services show whether a return has been received, is being processed, or has been issued, which distinguishes a delay from the ordinary progress of a queue.
- Verify the bank details on file. This is the single check that can be completed before waiting begins and the one most likely to matter under the 90-day provision.
- Wait for day 30 before telephoning. Before that point the service will not open an enquiry, and after it the call can be made with the return’s reference details at hand.
- Where financial difficulty exists, ask. The system includes hardship provisions, and a taxpayer who needs the money for essentials is in a different category from one who would prefer it sooner.
The clock the ATO keeps
The clock is the answer, and it is a clock kept in business days. Most electronic returns are processed within 12 of them, enquiries about delay begin at day 30, and the intervening time is spent on verification that no telephone call can accelerate. Almost everything that feels wrong to a waiting taxpayer is the arithmetic of two calendars running at different speeds.
The habits that keep a refund ordinary are unglamorous: lodge accurate figures once, keep the bank details current, and read the outcome rather than the rumour. A refund that arrives within the published window and matches the return is the least interesting document of the year, and that is precisely the standard the system is built to deliver.
Sources: Australian Taxation Office – check the progress of your tax return; Australian Taxation Office – refund retention and bank account details guidance; Treasury Laws Amendment (2024 Tax and Other Measures No. 1) Act 2024.
A taxpayer may prepare and lodge a return without assistance. Most do, and for straightforward employment income the process is short. The question this article addresses is narrower: at what point does the complexity of an individual’s or a business’s affairs justify the cost of a registered tax agent, and what is being purchased when that fee is paid.
1. The test is complexity, not income
The presence of a large salary does not by itself create a need for an agent, and the absence of one does not remove it. What moves an individual into the territory where a fee is defensible is the number of moving parts, and the likelihood that an error will be costly to correct.
The following circumstances are those in which an agent’s involvement is most commonly justified:
- Rental property income, particularly where there is a loan, a depreciation schedule or a period of private use to apportion.
- Business or sole trader income, which brings record-keeping, deductions, and possibly GST obligations with it.
- Income from several sources at once, including a side activity that has grown beyond a hobby.
- Investments, including shares and digital assets, where each disposal may have its own cost base and holding period.
- Foreign income, foreign assets or a period of overseas residence.
- A previous return that was lodged incorrectly and now needs amendment.
- Correspondence from the Australian Taxation Office that the taxpayer does not understand or does not wish to answer alone.
Two of those items are not about arithmetic at all. An amendment or an ATO review changes the cost of an error from a small correction to a process with deadlines, and that is where an agent’s value is most obvious.
2. Registration is the first thing to verify
Tax agent services may only be provided by a person registered with the Tax Practitioners Board, and the Board maintains a public register that any taxpayer may search at no cost. A person who is not registered cannot lawfully charge a fee for that service. Verification takes a minute and it is the single most useful check available before any engagement begins.
Where an activity statement is involved, the practitioner’s registration should also cover business activity statement services. A practitioner registered for income tax only may not be the correct person for that work, and the register records which services each practitioner is registered to provide.
3. What the taxpayer remains responsible for
Engaging an agent does not transfer responsibility for the content of a return. The taxpayer signs the declaration, and the declaration states that the information provided is true and complete. An agent works from the information supplied, and an agent who is given incomplete records cannot produce a complete return.
Where a registered agent is engaged and the taxpayer has supplied complete and accurate information, Australian law provides a measure of protection from certain administrative penalties arising from the agent’s own error. That protection is conditional on the information given, which is why the quality of the records handed over is the taxpayer’s most important contribution to the process.
4. What the fee covers
The visible part of the service is the preparation and lodgement of the return. Several less visible elements usually sit behind it.
- Lodgement dates under the ATO’s agent programme, which are generally later than the public due date for taxpayers represented by a registered agent.
- A nominated point of contact, so that ATO correspondence is directed to the practice rather than the taxpayer’s letterbox.
- Access to practitioner services and a dedicated telephone queue for registered agents.
- Ongoing record-keeping guidance during the year, which is where most avoidable errors are prevented.
- Professional indemnity arrangements, which an unregistered preparer does not carry in the same form.
A taxpayer who engages an agent only in July is buying a lodgement service. A taxpayer who speaks to the same agent in March is buying advice while there is still time to act on it. The second is usually the more valuable purchase, and the fee is often the same.
5. Fixed fee or hourly rate, and what to ask before signing
Both fee structures are legitimate, and the point is to know which applies before work begins. The following questions are the ones that resolve the engagement.
- Is the fee fixed, and what would cause it to change?
- Who will do the work: the practitioner whose name is on the door, or a junior under supervision?
- What records are required, and in what format?
- What happens, and what is charged, if the ATO reviews the return?
- How are amendments handled, and at whose cost when the error was the practice’s?
- Is the practice registered to provide the other services required, such as activity statements?
6. Which parts of the invoice are deductible
The cost of managing an individual’s tax affairs is generally deductible, and that commonly includes the preparation and lodgement fee. The position is less clear where the work is advice about a decision that has not yet been made, such as whether to acquire an asset, because that advice may relate to a future capital matter rather than to the management of existing tax affairs.
The practical step is to ask the practice to separate the invoice into the components, so that each is treated according to what it is. A single undifferentiated figure is convenient and less useful. Where a deduction is claimed, the rules on record-keeping apply as they do to any other claim, and the broader account of commonly missed deductions and offsets is set out in a companion piece.
7. When a business should move past the lodgement question
For a business, the decision is rarely whether to engage a practitioner at all. It is whether the existing arrangement covers the obligations the business has acquired. Equipment financing is a useful example, because the tax and GST treatment differs between a chattel mortgage, a hire purchase and a lease, and the structure is usually chosen before the tax consequence is discussed. A business that is arranging vehicle finance while completing its own activity statements is likely to benefit from a single practitioner who sees both.
The point at which help pays
The fee is defensible when the cost of an error, in penalties, interest and time, exceeds the cost of the preparation. For a single employer and one bank account, it usually does not. For a rental property, a business, a share portfolio and an ATO letter arriving in the same year, it almost always does. The middle ground is decided by the records, because an agent charges for sorting out what was not kept.
Sources: the Tax Practitioners Board maintains the public register of registered tax and business activity statement agents at tpb.gov.au; the Australian Taxation Office publishes guidance on deductions, lodgement dates and the penalty protections that apply where a registered agent is engaged, at ato.gov.au.


 Healthcare1 year ago
SIL Providers: What to Compare Before You Commit
- Healthcare1 year ago
What Is Physiotherapy?
- Healthcare1 year ago
What a Dental Implant Replacement Costs in Melbourne
- Food1 year ago
Budget Bites: Delicious Meals You Can Cook for Under $10
- Tech1 year ago
Mental Health Apps and Wearables: What to Trust
- Healthcare1 year ago
What Changes When You Start SIL
- Home & Garden1 year ago
Gutter Upgrades Worth Doing Before You Sell
- Healthcare1 year ago
How to Put NDIS Community Participation Funding to Work