Electric Vehicles & Transport
The Full EV Tax Break on a Novated Lease Has a Use-By Date

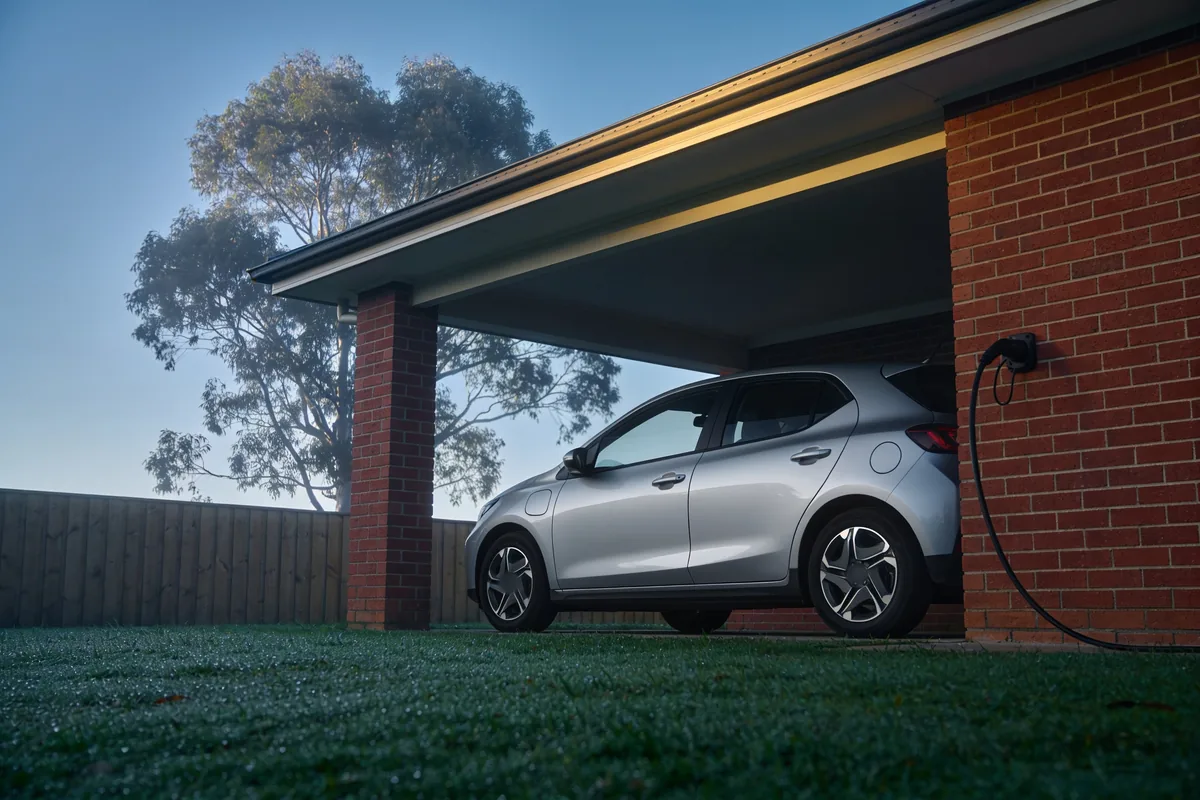
Two quotes for the same electric hatchback can sit side by side on an employee’s desk and differ in a way neither of them prints. One assumes the lease begins this financial year. The other was prepared for a start after March 2027. Under the fringe benefits tax exemption as it currently applies, the two would be treated alike. Under the phase-down the Treasurer announced on 5 May 2026, they may not be. The start date is the variable that separates them, and the change it turns on is announced policy, not law: the phases are set to begin on 1 April 2027, and the legislation behind them has not passed. What follows places the current rule, the three announced phases and the costs the exemption never removed next to one another, so that a novated lease EV quote can be read against all of them at once.
Your EV lease questions, before you sign
Five quick answers. The list below turns them into the questions to put to your lease provider and your employer.
If the questions do not load, the same checks are set out in the article below, one under each heading.
Answer the questions and your summary will appear here.
The changes behind these questions are announced policy, not law. The answers belong to your provider, your employer and the law as passed.
Your answers stay on this page and are not stored or sent anywhere.
What the exemption covers today
The ATO describes the exemption in conditions, and each one does work. The car must be a battery electric vehicle or a hydrogen fuel cell electric vehicle. It must have been first held and used on or after 1 July 2022. And luxury car tax must never have been payable on it. Salary packaging is included, which is how a novated lease delivers the car to an employee, so where the conditions are met, no fringe benefits tax is payable on the car’s private use. The exemption reaches past the car itself to its running costs, including the electricity used to charge it at home.
The luxury car tax condition is the first place price enters the subject, and it enters indirectly. The ATO’s luxury car tax threshold table sets the fuel-efficient vehicle threshold at $91,387 for 2025-26 and $91,661 for 2026-27. The exemption turns on whether that tax was payable on a particular car, so the threshold is a line to check against rather than a figure to read off a brochure, and the lease provider is the party that should confirm which side of it a given car sits.
Plug-in hybrids are the exception most likely to catch a buyer who assumes that “electric” covers them. From 1 April 2025, the ATO no longer treats a plug-in hybrid as a zero or low emissions vehicle for the purposes of the exemption. Transitional conditions apply to some arrangements, and the ATO sets those out. An employee weighing a plug-in hybrid against a battery electric car should therefore establish whether any exemption applies to the hybrid at all before the two quotes are compared on anything else.
One further line on the ATO page matters for the rest of this article: the benefit, although exempt, remains reportable. That line is taken up in the fourth section, because it is the part of the arrangement that the phase-down leaves untouched.
Three phases, side by side
The Treasurer’s release of 5 May 2026 sets out the phase-down in three stages. Set out together, they read as follows. Every row is announced policy, not law.
| Phase | Period, as announced | Treatment of an eligible electric car |
|---|---|---|
| One | Until the end of March 2027 | The exemption as it applies now |
| Two | 1 April 2027 to 1 April 2029 | Full exemption only for cars costing $75,000 or less. Above $75,000 and under the luxury car tax threshold, a 25 per cent discount on the FBT payable |
| Three | From 1 April 2029 | A 25 per cent discount for all eligible electric cars |
Two further statements qualify the table. The release states that existing leases won’t be impacted. The 2026-27 Budget papers add a condition to the second phase: cars costing up to $75,000 keep the full exemption “provided the fringe benefit arrangement commences before 1 April 2029”. Read together, the condition attaches to the date the arrangement commences rather than to the date a car is ordered or delivered, which is why the start date on a lease document deserves more attention than it ordinarily receives.
The 25 per cent figure in the second and third rows is a discount on the FBT that would otherwise be payable. It is a reduction of a tax amount, and the release does not set out how that amount is to be calculated for a particular lease. A quote that models the discount should show its working, and a reader comparing two quotes should check that both have used the same phase.
For context, the Budget counts the change as a saving of $1.7 billion over five years from 2025-26. The figure is the government’s, measured across every affected arrangement. It describes nothing about the effect on a single lease, and it should not be read as an estimate of what any one employee stands to lose.
What the $75,000 measures
The second phase turns on one number, and the announcement leaves its measurement open. Treasury’s wording is “costing $75,000 or less”. The release does not define which price that refers to. A lease quote can show more than one price for the same car, and the announcement does not say which of them the cap is set to read. This article does not state a basis, because the source does not.
Two practical consequences follow. First, a car priced close to $75,000 on one measure may sit on either side of the cap on another, so the margin matters more than the headline. A car well clear of the figure, in either direction, is less exposed to the question. Second, until the final law defines the measure, a provider’s statement that a car is “under the cap” is that provider’s reading of an announcement. That reading may prove correct, and it is still worth asking for two things in writing: the price the provider has measured against the cap, and the basis on which that price was chosen.
The comparison between two quotes is affected as well. If one provider measures one price and a second provider measures another, the two quotes can place the same car in different phases, and the difference in the bottom line can look like a difference in pricing when it is a difference in assumption. The quote and, once it exists, the final law are the documents that settle this. A summary of the announcement, this one included, cannot.
The cost the exemption never removed
The published lease comparisons on this subject lead with the exemption, and none of them sets beside the phases the one figure the exemption never removed. According to the ATO, an exempt car benefit is still reportable. Where the taxable value of an employee’s reportable fringe benefits is more than $2,000 in an FBT year, the employer reports it on the employee’s income statement as a reportable fringe benefits amount, grossed up at the lower rate before it is reported.
That amount is not part of the employee’s assessable income, so it adds no income tax. It is, however, counted in a long list of income tests. The ATO’s page on the consequences of having a reportable fringe benefits amount names, among others:
- the Medicare levy surcharge and the private health insurance rebate
- Division 293 tax
- repayments of HELP and the other study and training support loans
- family assistance, including Family Tax Benefit Parts A and B, the Child Care Subsidy and Parental Leave Pay
- child support
For an employee with none of these in play, the reportable amount may change little. For one who repays a study loan, the effect can run against the headline: an amount that adds no income tax can still lift the income on which a compulsory repayment is assessed. The other half of that calculation, how the balance itself moves each year, is set out in the piece on HECS indexation and the 1 June date, and the two are worth reading together by anyone with a balance still open. The same logic applies to a household near a family assistance threshold, and to a single earner whose income sits close to the Medicare levy surcharge line.
None of this is new, and the announcement does not change any of it. It belongs beside the phases because a full exemption and a reportable amount arrive together. A quote that shows the first without the second is describing half of the arrangement, and it is the half that looks better.
How the timing plays out
Set against the table, the announced design produces four broad positions for an employee signing a novated lease on an eligible electric car. They are stated below in the terms the release and the Budget papers use, without dollar modelling, because any modelling depends on prices and definitions that have not yet been settled.
Signed before April 2027. The arrangement begins in the first phase, and the release’s statement that existing leases won’t be impacted is the line that applies. What counts as an existing lease, and whether a later change to that lease keeps it in the category, is a matter for the final law. The sixth section returns to it.
Costing $75,000 or less, signed from April 2027 and before April 2029. On the announced design, the full exemption continues, and the Budget papers tie it to an arrangement that commences before 1 April 2029. The measurement question from the third section is the live one here, because this is the position in which a car’s price, on whichever measure applies, decides the outcome.
Costing more than $75,000 and under the luxury car tax threshold, signed in the same window. The exemption gives way to the 25 per cent discount on the FBT payable. The lease remains available, and the tax position is different from the one a first-phase quote would describe. A quote prepared before the announcement, or on first-phase assumptions, is not a guide to a lease that starts in this window.
Signed from April 2029. On the announced design, the 25 per cent discount applies to all eligible electric cars, and the full exemption is no longer the reference point for a new lease.
Laid out this way, the four positions show what the start date controls and what it does not. It decides which phase an arrangement falls into. It does not decide the reportable amount, which runs through all four, or the open questions in the next section, which none of the four resolves.
A novated lease is one route to a car, and a reader working through these positions may reasonably set it beside the plainer one. An employee who finds the post-2027 position less attractive, or who expects to change employer within the term, can weigh ordinary finance instead. The steps that bear on that path are covered in how to improve your chances of car loan approval in 30 days, and comparing both routes on the same car is a more useful exercise than comparing two lease quotes alone.
What the announcement leaves open
The release answers the question it was written to answer and leaves several others open. The plainest of them sits in the title of a forum thread on this subject: what happens to the FBT exemption on an EV novated lease when the employee changes jobs.
The question has weight because a novated lease is delivered through salary packaging with a particular employer. A change of employer therefore changes the arrangement the exemption attaches to. Whether a lease that moves to a new employer after 1 April 2027 still counts as an existing lease, in the release’s sense, is not addressed in the announcement. Nor is the position of a lease that cannot move and has to end.
The end of the term raises a parallel question. Extending a lease, or refinancing the residual to keep the car, may or may not count as a new arrangement commencing on a new date. The answer matters, because the Budget papers tie the full exemption for cars under the cap to the date an arrangement commences, and a new commencement date could place an existing car in a different phase.
These are open questions, and this article does not answer them, because the sources do not. The final legislation, once passed, and the provider’s own terms are where the answers belong. Questions of this kind, where a contract meets a tax rule that is not yet law, are a reasonable illustration of when a tax agent earns their fee: the value lies less in the arithmetic than in reading a specific arrangement against rules that are still being settled.
Before the paperwork
Three checks, one line each:
- Ask which phase the quote assumes, and on what lease start date.
- Ask for the price measured against the $75,000 cap, and the basis for choosing it.
- Ask for an estimate of the reportable fringe benefits amount, and test it against any study loan, family payment or surcharge line.
This article is general information, not financial or tax advice. The lease provider or a registered tax agent should confirm any individual position, and the announced changes should be read against the law as it is eventually passed rather than against the release alone.
Sources: Fairer tax treatment to encourage affordable EVs, Treasurer media release, 5 May 2026 (https://ministers.treasury.gov.au/ministers/jim-chalmers-2022/media-releases/fairer-tax-treatment-encourage-affordable-evs); ATO, Electric cars exemption (https://www.ato.gov.au/businesses-and-organisations/hiring-and-paying-your-workers/fringe-benefits-tax/types-of-fringe-benefits/fbt-on-cars-other-vehicles-parking-and-tolls/electric-cars-exemption); ATO, Consequences of having a reportable fringe benefits amount (https://www.ato.gov.au/individuals-and-families/jobs-and-employment-types/working-as-an-employee/reportable-fringe-benefits-for-employees/consequences-of-having-a-reportable-fringe-benefits-amount)


 Healthcare1 year ago
SIL Providers: What to Compare Before You Commit
- Healthcare1 year ago
What Is Physiotherapy?
- Healthcare1 year ago
What a Dental Implant Replacement Costs in Melbourne
- Healthcare1 year ago
What Changes When You Start SIL
- Food1 year ago
Budget Bites: Delicious Meals You Can Cook for Under $10
- Tech1 year ago
Mental Health Apps and Wearables: What to Trust
- Home & Garden1 year ago
Gutter Upgrades Worth Doing Before You Sell
- Healthcare1 year ago
How to Put NDIS Community Participation Funding to Work





You must be logged in to post a comment Login