Personal Finance
Extended Warranties Mostly Sell You Rights the Consumer Guarantees Give Free

1. The position
In most cases, a buyer offered an extended warranty on an appliance or a piece of electronics at the counter should decline it. The consumer guarantees in the Australian Consumer Law already cover a faulty product for a reasonable time, whether or not any warranty was bought, and they continue to apply after the maker’s warranty has ended. A paid plan is worth considering only where it supplies something the law does not, and the main example of that is accidental damage.
That is not a fringe view. Asked whether an extended warranty is needed, CHOICE answers: “In most cases, probably not.” Consumer Protection WA and the NSW Government say much the same thing in their own guidance. The paid plan is optional. The legal protection is not.
The difficulty is that many buyers do not know this. A CHOICE survey published in 2023 found that 68% of respondents wrongly believed an extended warranty gives more protection than the Australian Consumer Law, and 70% thought no remedy was available once the manufacturer’s warranty had expired. Only 12% of those who bought in store said they had been told how the plan differed from their rights under the law. An offer made at the point of sale meets a buyer who, more often than not, underestimates what they already hold.
What follows is general information, not legal advice. A buyer with a particular dispute should contact the fair trading or consumer protection body in their state or territory.
2. What the consumer guarantees are
The consumer guarantees are automatic. They attach to the sale without being asked for, and a business cannot exclude them by contract, by a sign at the register, or by anything said at the counter.
The seller guarantees that the goods:
- are of acceptable quality;
- are fit for any purpose the buyer made known, or that the seller said they would be fit for;
- match their description, and any sample or demonstration model; and
- come with clear title, so that the buyer actually owns them.
The manufacturer carries guarantees as well. According to Consumer Protection WA, these include making spare parts and repair facilities available for a reasonable time.
Two practical consequences follow. First, a “no refunds” sign does not remove these rights. Second, WA states that a business must not mislead a buyer by “saying the consumer must buy an extended warranty to avoid losing these basic rights”. Any sales script that suggests otherwise is wrong on the law.
The guarantees also set out who chooses the remedy. Where a failure is minor, the business may choose whether to repair, replace or refund. Where a failure is major, the buyer chooses between a refund and a replacement, or may keep the product and seek compensation for the drop in its value. CHOICE explains this distinction in its guidance, and it matters, because a paid plan that only offers repair may give the buyer less choice than the law does for a major failure.
This article deals with appliances and electronics. Motor vehicles raise their own questions about servicing and manufacturer conditions, which are covered separately in logbook servicing, warranty and the fine print.
3. How long “reasonable time” runs
The consumer guarantees do not end on a fixed date. There is no list in the law that says a fridge is covered for so many years or a laptop for so many months. The question in each case is whether the product was of acceptable quality, judged against what a reasonable consumer would expect.
CHOICE identifies the factors that shape that expectation:
- the type of product;
- the price paid; and
- how long a regular customer would expect a product of that kind to last.
Those factors come from the law itself. Section 54 of the Australian Consumer Law (Schedule 2 to the Competition and Consumer Act 2010) provides that goods are of acceptable quality if they are fit for all the purposes for which goods of that kind are commonly supplied, acceptable in appearance and finish, free from defects, safe and durable, as a reasonable consumer fully acquainted with their state and condition would regard as acceptable. Section 54(3) lists the matters to be weighed: the nature of the goods, the price (if relevant), statements on any packaging or label, representations made by the supplier or manufacturer, and any other relevant circumstances. Durability is the word that does the work here. It is the reason the guarantees can run past the end of the maker’s warranty.
Most guidance stops there, with the phrase “it depends”. The regulators, however, have given concrete illustrations, and they are more useful than the phrase.
The first comes from Consumer Protection WA. It describes a $2,000 television with a 12-month manufacturer’s warranty that develops a fault at 18 months. The WA Commissioner’s position is that “consumer law will already protect the purchase because it is reasonable to expect an expensive TV to last longer than one year”. The maker’s warranty has expired. The buyer’s rights have not.
The second comes from CHOICE, which reports that ACCC guidance suggests a buyer could expect an expensive television to last more than two years.
Neither example is a rule for every television, and neither sets a figure for other products. What they show is the method. Price and product type lift the expectation, and an expensive item is expected to last longer than its warranty period.
A ruling on the rules of thumb
In consumer discussion online, three shortcuts circulate as if they were the test. None of them is.
- The ATO effective-life table. That table exists to set depreciation for tax purposes. It says nothing about what a buyer is entitled to expect from a product under consumer law.
- The length of the manufacturer’s warranty. The maker’s warranty is a commercial promise the maker chooses to offer. It sits on top of the guarantees and does not define them. The WA television example exists precisely because the two diverge.
- “A court said X years.” Figures said to come from a particular decision are repeated widely. A decision turns on the product, the price and the facts in front of the court, and it does not set a general period for everything in the same category.
The test remains what a reasonable consumer would expect for that type of product at that price. A buyer who keeps that question in mind is better placed than one who relies on a number from any of the three sources above.
4. The overlap, worked (a hypothetical example)
The following example is hypothetical. The figures are chosen to illustrate the method and do not describe any actual product, retailer or plan.
A buyer purchases a fridge for $1,800. It carries a two-year manufacturer’s warranty. At the counter, the buyer is offered a plan that extends cover to the end of year five for $249. Because the first two years are already under the maker’s warranty, the plan in practice covers years three, four and five. That is $249 for three years, or $83 a year.
The useful question is not whether $83 a year sounds reasonable. It is this: for each of those paid years, would a reasonable buyer already expect an $1,800 fridge to be working?
| Paid year | Question to ask | If the answer is yes | If the answer is no |
|---|---|---|---|
| Year 3 | Would a reasonable buyer expect an $1,800 fridge to still be of acceptable quality? | The guarantees already apply. The plan buys procedure, not rights | The plan may add cover the law does not give |
| Year 4 | The same question | As above | As above |
| Year 5 | The same question | As above | As above |
Wherever the honest answer is yes, the buyer is paying for a second route to a remedy that the law already provides. The plan may offer a different claim process, a call centre or a fixed set of terms. It does not offer a right the buyer lacked.
Two findings from CHOICE sharpen the point. First, CHOICE reports that most extended warranties run for around two or three years from the date of purchase, which places much of their cover inside the period in which a fault would usually be the clearest case under the guarantees. Second, in its 2023 survey, 72% of those who had claimed on an extended warranty did so while the product was less than two years old.
CHOICE also offers a simple rule for the other end of the price range: compare the cost of the plan with the cost of replacing the item. A $20 plan on a $20 rice cooker makes little sense on any reading of the law.
5. Where paid cover can earn its price
There are situations in which a paid plan can add something the guarantees do not. Each of the following applies only if the plan document actually says so.
- Accidental damage. This is the main gap. The consumer guarantees do not apply where the buyer “misused a product in any way that caused the problem”, according to the NSW Government, and section 54(6) of the Australian Consumer Law makes the same point about damage the consumer causes and abnormal use. A dropped laptop or a television knocked off its stand is not a failure of acceptable quality. A plan that genuinely covers accidental damage covers something the law leaves out. Many plans do not, and a buyer should not assume it.
- A loan or replacement unit. The guarantees are framed around a remedy for the fault itself. A plan that promises, in writing, a working unit on loan while the original is assessed or repaired may be worth something to a household that cannot manage without one.
- Home service or removal and reinstallation. For built-in appliances, the cost and inconvenience of removal and reinstallation can be significant. A plan that covers these clearly, in writing, adds practical value.
- Avoiding a dispute. Claiming under the guarantees can involve an assessment, a discussion about whether a fault is minor or major, and a wait for repair. A plan with defined terms can remove part of the argument about what “reasonable” means for a particular product.
The last of these is the fair point on the other side, and it deserves to be stated plainly. In consumer discussion online, one group of buyers says they purchase extended warranties for convenience, not for rights, because pursuing a claim under the law can take time. That is a legitimate preference. It is, however, a payment for procedure, and the buyer should know that this is what is being bought.
6. Questions at the checkout
Drawing on the guidance from the NSW Government, Consumer Protection WA and CHOICE, a buyer offered a plan should be able to answer each of the following before agreeing.
- Who provides it? It is often a third party, not the retailer.
- When does it start? A plan may begin on the date of purchase, which overlaps the maker’s warranty, or only when that warranty ends.
- What will a claim cost? Check for an excess, call-out fees, labour, and installation or removal costs.
- What is excluded, and what are the limits? Look for claim caps, a limit on the number of claims, and whether accidental damage is in or out.
- Is a replacement depreciated? Some plans pay less than the original price as the product ages.
- Who can do the repair? Some plans restrict the buyer to particular repairers.
- Can a claim cancel the plan? WA warns that “some claims during the manufacturer’s warranty could cancel the extended warranty”.
- What is it called? WA notes that some plans are now sold as “product care” or a similar name. The label does not change what the document must be checked for.
The habit of reading exclusions before paying applies well beyond appliances, and the same discipline that suits travel insurance exclusions suits a plan offered at the register.
CHOICE suggests one question for the salesperson that covers most of the list above: “What protection does this give me beyond the ACL?” A clear and specific answer is a good sign, and a vague one tells the buyer to look harder at the document. In either case, NSW advises relying on the written document, not on what was said at the counter. The NSW Government also states that an extended warranty “does not replace your rights under consumer guarantees”.
The offer tends to come most often in the busy shopping weeks at the end of the year, which is a good reason to settle on these questions before going in.
7. When something fails
Where a product develops a fault, the steps are the same whether or not a plan was bought.
- Go to the seller first, under the Australian Consumer Law. WA states that buyers hold their entitlements under the law “regardless of any extended warranty, and even if the manufacturer’s warranty has expired”. A seller who directs the buyer only to the plan, or only to the maker, has not answered the buyer’s legal claim.
- Bring proof of purchase. A receipt is best, but CHOICE notes that a card statement can serve.
- Escalate if necessary. If the seller does not resolve the matter, the next step is the fair trading or consumer protection body in the buyer’s state or territory.
A buyer who has already purchased a plan and now wishes to cancel it should read the plan’s own terms for any cooling-off or cancellation period. Whether one exists, and on what conditions, depends on the plan, and it should not be assumed to be available as a general legal right.
8. What the extra money should buy
The rights a buyer most needs when a product fails early are already included in the purchase price. They do not need to be bought twice. For the large majority of faults, the consumer guarantees provide a remedy for a reasonable time, and that time can run well past the maker’s warranty for an expensive product.
The extra money should therefore buy only what the law leaves out. Accidental damage is the clearest case. A loan unit, home service, or removal and reinstallation of a built-in appliance may also be worth paying for, provided the document says so in plain terms. Where a plan cannot point to anything of that kind, the buyer is paying for a second copy of rights already held, and the sensible answer at the counter is a polite no.
Sources: Do you need an extended warranty?, CHOICE (https://www.choice.com.au/shopping/consumer-rights-and-advice/your-rights/buying-guides/do-you-need-an-extended-warranty); 7 out of 10 people wrongly believe buying an extended warranty provides extra protections, CHOICE, 2 August 2023 (https://www.choice.com.au/about-us/media/media-releases/2023/august/extended-warranties); Consumer guarantees, Consumer Protection WA (https://www.consumerprotection.wa.gov.au/consumer-guarantees); Commissioner’s blog: Say ‘no’ to extended warranties, Government of Western Australia (https://www.wa.gov.au/government/announcements/commissioners-blog-say-no-extended-warranties); From the Commissioner: Extended Warranties, worth it or worthless?, Government of Western Australia (https://www.wa.gov.au/government/announcements/the-commissioner-extended-warranties-worth-it-or-worthless); Signing up for an extended warranty or care package, NSW Government (https://www.nsw.gov.au/legal-and-justice/consumer-rights-and-protection/be-a-smart-consumer/signing-up-for-an-extended-warranty-or-care-package); Consumer guarantees, NSW Government (https://www.nsw.gov.au/legal-and-justice/consumer-rights-and-protection/guarantees-contracts-and-warranties/consumer-guarantees); Competition and Consumer Act 2010, Schedule 2 (Australian Consumer Law), section 54, Federal Register of Legislation (https://www.legislation.gov.au/C2004A00109/latest/text)
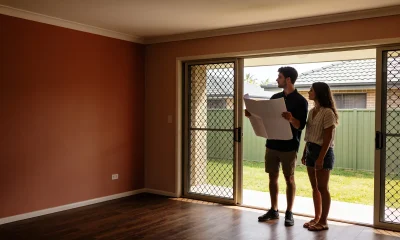




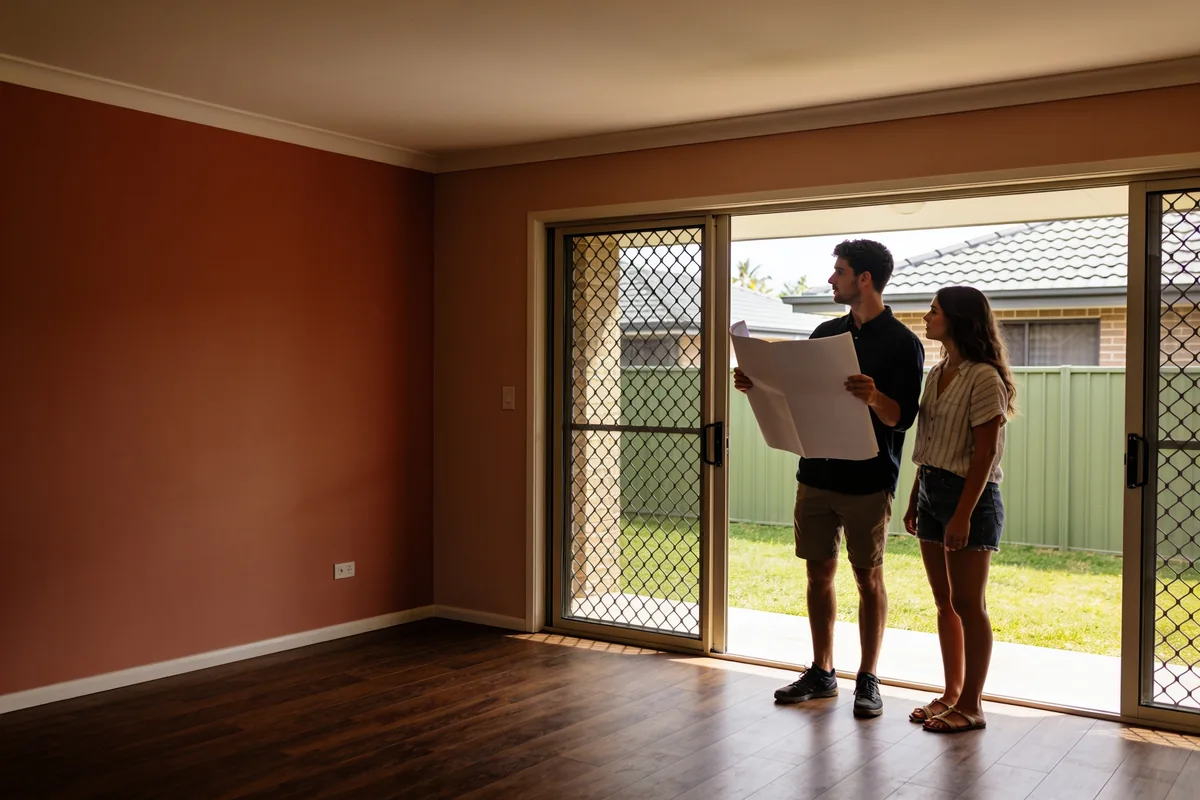
The agent has propped the front door open with a wedge, and the hallway smells faintly of fresh paint and someone else’s coffee. It is a Saturday morning in a newer estate, the kind where the trees along the nature strip are still tied to stakes. Inside, a dozen people move through the rooms in that careful, slightly guilty way people do at open homes, touching nothing, opening every cupboard with their eyes.
In the kitchen, a couple in their late twenties have stopped by the window. She has the price guide folded into a small square in her palm. He is doing sums under his breath. They have saved for four years, and what they have is enough for a deposit of about five per cent. For most of those four years, they had assumed that five per cent was not really enough, that the bank would want twenty, or would make them pay for insurance to cover the gap. The question they are whispering is the one thousands of first buyers ask: can we actually do this?
Since 1 October 2025, the honest answer has changed for a lot of people in that kitchen. What the old scheme was called, what it does now, and what it still cannot do for them are worth knowing before they make an offer.
What changed on 1 October 2025
The scheme many people still search for as the First Home Guarantee has a new name. According to the government’s First Home Buyers site, it is now the Australian Government 5% Deposit Scheme, formerly the Home Guarantee Scheme.
The name is the smallest of the changes. From 1 October 2025, the official site lists three things the scheme no longer has:
- No income caps. What you earn no longer decides whether you can use it.
- No waitlists. Places are unlimited, so there is no queue to join.
- No Lenders Mortgage Insurance. The cost that usually comes with a small deposit does not apply to a loan under the scheme.
That third point is the one the couple in the kitchen did not know about. Lenders Mortgage Insurance, or LMI, is the premium a lender usually asks a borrower to pay when the deposit is small. Under the scheme, a government guarantee stands in its place. The official site says it has helped more than 320,000 Australians since 2020.
Who it is for
The scheme is built for two groups:
- First home buyers with a minimum deposit of 5%.
- Single parents or legal guardians with a minimum deposit of 2%.
There are further eligibility rules, covering things like citizenship or residency, age and whether you have owned property before. They are set out in the eligibility tool on the First Home Buyers site, and they are worth checking there, against your own circumstances, rather than from a summary like this one. The tool is quick, and it will tell you more reliably than any article whether you fit.
The price caps
This is where the couple’s price guide matters. The scheme has a limit on the property price, and the limit depends on where the home is.
Two numbers have to sit at or below the cap: the purchase price, and the lender’s valuation. If you are buying land and building, it is the combined total that counts. These are the caps as the official site lists them:
| State or territory | Capital city and regional centres | Rest of state |
|---|---|---|
| NSW | $1,500,000 | $800,000 |
| Victoria | $950,000 | $650,000 |
| Queensland | $1,000,000 | $700,000 |
| Western Australia | $850,000 | $600,000 |
| South Australia | $900,000 | $500,000 |
| Tasmania | $700,000 | $550,000 |
| ACT | $1,000,000 | |
| Northern Territory | $750,000 (Darwin) | $600,000 |
| Jervis Bay and Norfolk Island | $550,000 | |
| Christmas and Cocos (Keeling) Islands | $400,000 |
“Regional centres” has a specific meaning here. For NSW, the higher cap applies to the Central Coast, Coffs Harbour-Grafton, Illawarra, the Mid North Coast, Richmond-Tweed, and Newcastle and Lake Macquarie. For Victoria it covers Geelong. For Queensland it covers the Gold Coast and the Sunshine Coast.
So a home in Geelong sits under the same cap as one in Melbourne, while a home elsewhere in regional Victoria sits under the lower one. A couple looking along the coast in NSW may find the line between the two caps runs closer to them than they think. The postcode decides, so check it before you fall for the kitchen.
How it works
The scheme does not run through a government office. You apply through a Participating Lender, a bank or lender that has signed up to offer it. You do not apply to Housing Australia directly.
Once a lender pre-approves you under the scheme, the clock starts. The official site says you have 90 days to find a home and sign a contract. Ninety days sounds generous until the second weekend of inspections, so it is worth having a clear idea of the suburb and the cap before you seek pre-approval, not after.
The lender still decides how much it will lend you, after its own look at your finances. The scheme changes what the deposit has to cover. It does not change whether the lender thinks you can make the repayments. If you have not been through a lender’s assessment before, the steps in how to improve your chances of car loan approval in 30 days cover the same habits a home lender looks at, on a smaller scale.
And the guarantee is exactly that, a guarantee to the lender. It is not a gift to you. The official site is clear that you remain responsible for all the costs of buying and for every repayment.
What it does not do
This is the part that tends to get lost in the excitement of the open home, and it is the part worth saying slowly.
It does not shrink the loan. A 5% deposit means borrowing 95% of the price. That is a bigger loan than someone with 20% down would take on for the same house, and a bigger loan means more interest over its life. That is plain arithmetic, and it holds whatever rates do.
It does not shrink the repayments. The scheme removes the LMI cost. It does not reduce what you owe each month on a larger balance.
It comes with ongoing obligations. The official site lists conditions that continue after you buy, such as living in the home as an owner-occupier. If you stop meeting them, the guarantee may no longer apply.
It is not Help to Buy. Help to Buy is a separate government scheme built on shared equity, and it works differently. If you have heard both names and assumed they were the same thing, they are not, and they are worth looking up separately.
Lenders will also count your other debts when they work out what you can borrow. A student loan is the one many first buyers forget, and the way that balance moves each year is set out in the piece on HECS indexation and the 1 June date. It is worth reading before you sit down with a lender, so the number does not surprise you in the meeting.
What buyers say
Numbers on a government page only tell part of it. The rest comes from people who have already done it, and in the online forums where first buyers compare notes, they have been talking.
In one thread asking people who had used the 5% scheme how they were feeling, the most popular reply came from someone who had bought for around $950,000 with five per cent down. They said they were absolutely fine. Their lender had assessed them against a buffer above the actual rate, they wrote, which had left them plenty of headroom, and they had bought a home to live in, not an investment. Another said their repayments were high, but that every one felt like it was paying for part of the house, one room at a time.
Not everyone sounded so settled. One borrower with a loan of about $380,000 said they were fine, but added that their loan was small, and they imagined people with $800,000 loans were not having as much fun. Another buyer described waiting until after Budget night to decide whether to go ahead, watching the market slow before they committed.
These are individual stories, not data, and they do not tell you how you would fare. What they do show is the shape of the experience: comfort tends to depend on the size of the loan against the household’s income, and on how much room the lender’s assessment left. The scheme makes the deposit smaller. The loan is the part you live with.
Before the pre-approval clock starts
Back in the kitchen, the couple are still at the window. The price guide is unfolded now, smoothed flat on the bench. They are not going to make an offer today. They are going home to check three things first.
The price cap for the postcode. They will find the cap for this suburb on the official list, and check whether it is a capital city or regional centre or the rest of the state. Then they will make sure both the price they might pay and the bank’s valuation could sit under it.
That the lender is participating. They will confirm that the bank they want to use is a Participating Lender for the scheme before they ask for pre-approval, because the scheme only runs through those lenders.
The budget at the repayment, not the deposit. They will work out what the repayment on a 95% loan would cost them each month, and whether they could carry it on a bad month as well as a good one. The deposit got them in the door. The repayment is what they will be paying long after the open home is forgotten.
Then, and only then, they will ask for pre-approval, and the 90 days will begin.
This article is general information, not financial advice. Check your own eligibility on the official First Home Buyers site, and talk to a Participating Lender or a licensed adviser about your circumstances.
Sources: Australian Government 5% Deposit Scheme, First Home Buyers, Australian Government (https://firsthomebuyers.gov.au/australian-government-5-percent-deposit-scheme); Property price caps, First Home Buyers, Australian Government (https://firsthomebuyers.gov.au/australian-government-5-percent-deposit-scheme/property-price-caps)

One date a year moves some HELP balances further than twelve months of repayments move them back. Indexation is applied to study and training loans on 1 June, and the factor set for 1 June 2026 is 2.8 per cent, the lowest it has been since 2021.
Two properties of the mechanism keep it simpler than its reputation suggests. It is not interest, and it does not compound. It is applied once a year to a balance calculated on a single day, which reduces the planning question to a narrow one: what the balance is on the morning of 1 June, and whether anything can be done about its size before then.
The arithmetic most borrowers have never seen, stated plainly: 2.8 per cent adds $840 to a $30,000 balance, and $1,400 to a balance of $50,000. Against those figures sits a system in which most repayments are deducted quietly from wages across the year. The adjustment happens in one morning, and the repayments that were meant to answer it may not have been counted by that morning at all.
What indexation is, and what it is not
Indexation is the annual adjustment of an unpaid loan balance to account for changes in prices and wages. The ATO applies it on 1 June each year, and it applies to the portion of the balance that has been unpaid for more than 11 months. The newest debt therefore sits outside the calculation, and the factor multiplies what has been outstanding longer.
Three properties deserve separate statements, because each one is a place where expectation and mechanism part company. There is no compounding: each year’s factor applies to the balance as it stands, not to an accumulating interest bill, so the adjustment is a step rather than a curve. There is no accrual between steps: nothing is added monthly, weekly or daily, so a payment made in April changes the same balance a payment made in May changes. And the word the ATO uses, indexation, is exact: the factor is set by reference to published economic measures, not by a lender’s margin.
The factor for 1 June 2026 is 2.8 per cent. Two measures sat behind it. The consumer price index factor for the year was 2.8 per cent, and the wage price index factor was 3.4 per cent. Since the 2024 change to the law, the lower of the two measures is the one that applies, and that change is why the 2026 factor is the lowest since 2021. Before the change, the wage measure alone could have produced a factor of 3.4 per cent for the same year.
| 1 June | Indexation factor |
|---|---|
| 2021 | 0.6 per cent |
| 2023 | 7.1 per cent as first set, backdated to 3.2 per cent by the 2024 reform |
| 2024 | 4.0 per cent |
| 2025 | 3.2 per cent |
| 2026 | 2.8 per cent |
The table’s lesson is the range. A factor near 7 per cent, as first set for 2023, adds several times more to a large balance than the 2.8 per cent of 2026, and nothing about the borrower’s behaviour changes between those years. The mechanism is the same in every year; only the published number moves, which is why the figure is worth checking in April rather than discovering in June.
One separate measure belongs in the same section, because it shapes balances rather than rates. A one-off 20 per cent reduction was applied to study and training loan balances from 1 June 2025, before that year’s indexation, automatically and without application. It was a single measure rather than a recurring one, and a borrower who noticed their balance fall across mid-2025 was watching that change, not an error.
The factor is also not a surprise, which is worth knowing while the date is still ahead. The 2026 rate was set by a legislative instrument made in April, and it was public weeks before it was applied. The number for any year can be checked while there is still time to act on it, which is the difference between planning around 1 June and being told about it afterwards.
The scope is worth one sentence for completeness. The mechanics described here cover HELP and the other study and training loans the ATO administers, and the 1 June date is common to them. A single balance under one of those headings behaves the way this article describes, whatever the loan is called on a statement.
The balance that counts
Which balance the ATO indexes is the part of the system most often misunderstood, and the misunderstanding is expensive in exactly one month of the year. The figure that matters is the balance the ATO holds on 1 June. Repayments withheld from wages during the year do not reduce that figure as they are withheld; they reduce it when the tax return that accounts for them is processed.
The distinction sounds administrative and is not. A withholding that has been arriving in the system all year has, by 1 June, not yet touched the number the factor multiplies, because the return that credits it is lodged after the date. The compulsory system is doing its work on its own timetable, and that timetable runs through the return rather than through the calendar month of May.
The 11-month rule produces one more wrinkle worth naming alongside it. Debt from the most recent period of study sits outside the calculation until it ages past that threshold, so two borrowers can show the same headline balance while the portion of it being indexed differs between them. The newer debt is the sheltered debt, and the shelter expires on its own schedule.
A worked contrast makes the shape plain. Two people hold the same balance of $50,000 as May begins. The first does nothing, and indexation adds $1,400 on 1 June. The second pays $5,000 voluntarily in the middle of May, comfortably clear of the date, so the indexed balance is $45,000 and indexation adds $1,260. Both earned a similar wage through the year and had the same amounts withheld. The difference between them is the voluntary payment, and nothing else, because the withholdings were never in a position to help before the date.
The return is also where the two streams reconcile, and it is worth understanding that moment rather than dreading it. Withheld amounts are credited against the balance when the return is processed, and any overpayment comes back as a refund in the same motion. The site’s guide to the deductions and offsets people miss covers the return side of that arithmetic, which is a different subject from the balance side covered here.
Three positions, side by side
For any given year, a borrower is choosing between three positions, and each one carries a cost that the enthusiastic comparisons tend to leave out. The positions can be set side by side without recommending any of them, because the right one depends on facts the ATO does not hold: a household’s other debts, its cash position, and what is planned for the year.
The first position is a voluntary payment that clears before 1 June. Its benefit is precisely the indexation it avoids, which in a 2.8 per cent year is 2.8 per cent of the amount removed. For $5,000 paid in mid-May, the avoided indexation is $140. That figure, rather than any larger one, is the return on the move. What the comparison excludes is the other side of the ledger: the money leaves the household’s reach, and because HELP is otherwise interest-free, the payment buys no relief from interest and gives up flexibility in exchange for a small, certain saving.
The second position is to leave the balance alone, and it is the correct answer more often than the annual noise around indexation suggests. Two situations make it so. Where a refund from the same return is coming anyway, a voluntary payment and the refund can cross paths, leaving money to be returned shortly after it was spent. And where the same dollars would otherwise retire a debt charging more than 2.8 per cent, the indexation saving is the smaller of the two returns available. Neither situation is permanent, and both belong in the year’s arithmetic rather than in general advice.
The third position is a part-payment sized to the balance, which converts the decision into simple multiplication. Any amount that clears before 1 June removes 2.8 per cent of itself from that year’s adjustment; $2,000 removes $56, and $10,000 removes $280. The exercise is worth doing in dollars rather than in principle, because the saving is proportional and modest, and seeing the number keeps the decision in proportion with it.
The refund timing trap deserves one fuller sentence than it usually receives, because it is the point where good arithmetic and bad timing meet. A voluntary payment made in May and a refund arriving after the return is processed are two movements of the same money in opposite directions. Where the refund would have covered the payment anyway, the household has advanced the system money it was shortly going to receive, and the only return on the advance is the indexation avoided on the interval.
What none of the three positions changes is worth naming too. The compulsory system continues, the 11-month rule continues, and the timing of the withholding continues. The choice among the three is a one-year lever on one balance, pulled or not pulled, and the lever resets at the next 1 June.
A further consequence sits outside the debt and belongs in the same comparison for anyone borrowing this year. A HELP balance is assessed in lending calculations, so a household weighing a car loan in the same season is deciding between two uses of the same dollars. The site’s guide to improving the chances of car loan approval describes what lenders examine, and the HELP balance is one of the figures that changes the conversation.
The withholding you can switch off
One mechanism deserves its own section because it is the only lever aimed at the end of a debt rather than at a single year of it. A borrower whose balance is nearly completed can lodge a new Tax File Number Declaration with their employer, which stops the additional withholding that would otherwise continue through the payroll system.
The caution is the obvious one, stated once. The declaration removes the mechanism that was repaying the debt, so it suits a borrower who is genuinely close to the end and has checked the actual balance rather than inferred it from a payslip. Used too early, it converts an automatic repayment into an obligation settled at tax time, with the indexation in the meantime applied to a balance the withholding would otherwise have reduced.
The mechanic is worth understanding even for borrowers who never use it, because it explains the shape of the endgame. As a balance approaches zero, the withholding percentages applied through the payroll system can exceed what remains owed, and the excess comes back through the return. The declaration is the device that turns the final stretch into a straight line rather than a loop through the tax system.
Before 1 June
The date is the whole system, and it does not move. Indexation lands on 1 June against the balance the ATO holds that morning, at a factor published months earlier, and the levers available to a borrower are the size of the balance and the timing of any payment made against it. Voluntary payments need a few business days to clear, which places the practical deadline in the last week of May, and the useful decision point earlier than that.
What the arithmetic will not do is tell anyone whether paying early is right for their household. That depends on refund timing, competing debts and plans the ATO knows nothing about, which is why the three positions above are presented as a frame rather than a recommendation. What the mechanics do say, clearly, is which date matters and which payments land in time to matter. A calendar entry in April costs nothing and removes the only part of the system that can be missed by accident.
Sources: Australian Taxation Office – study and training loan indexation rates and the 2026 indexation factor; StudyAssist – HELP and study loan guidance; Australian Taxation Office – check the progress of your tax return.

A month is enough time to tidy a loan application. It is not enough time to rewrite your credit history, and anyone who tells you otherwise is selling something. What you can do is put your file in the best light it has ever been in.
Here are seven steps, in the order that helps most. Do them one at a time. None of them is difficult on its own.
1. Read your credit report first
Start with the file the lender will actually read. You can request a free copy of your credit report from each of the three credit reporting bodies, at the intervals the current credit reporting rules set, and each one can hold different information. Ask for one today. Reading it costs nothing.
Then look for the small errors that quietly cost money: a default that was paid and never updated, an address from years ago, a duplicate enquiry, an account that is not yours. A wrong entry is fixable. The fix starts with the bureau, which corrects the record with the lender’s confirmation. Follow the correction up in writing and keep the confirmation, because both the bureau and the lender take time to update their records, and an old entry can still be read as current until they do.
2. Deal with what the report shows
Lenders look at how you use credit, not just whether you have some. Balances sitting near their limits read as pressure, even when every payment has been on time. Paying a card down before you apply does more for the file than closing the account, and closing your oldest account can work against you. Small unpaid debts are the ones worth clearing first, because their size never matches the weight they carry.
3. Build the deposit
The size of your deposit shapes both the lender’s appetite and the deal you are offered. Steady saving shows more than a lump sum that arrived last week. If you have four weeks, set something aside each week rather than waiting for a windfall. The pattern is part of the application.
4. Get the documents into one folder
Identification, proof of income, bank statements, a letter from your employer, statements for any existing loans. Gather them into one place this week, even before you know which lender you are using. A complete file moves faster, and one missing document can park an application for a fortnight while the clock runs.
5. Compare the whole deal, not the rate
The advertised rate is the headline, and the comparison rate is the story: it folds in the fees and shows what the loan costs across the term. Ask for it. Then line up the same terms side by side, the same deposit, the same term, the same car, so you are comparing like with like instead of comparing ads.
Ask each lender what its comparison rate assumes, because the figure is built on a particular loan amount and term. Two quotes with different assumptions are not comparable, however close the headline numbers look.
If the car is really a vehicle for a business, the question changes shape, and how business vehicle finance differs is a separate read.
6. Keep the last month quiet
Every credit application leaves a mark on the file, including the ones you do not take up. Two cards and a new phone plan in the same fortnight tell a story you did not mean to write. If you can wait on the new credit until after settlement, wait. The finance itself is already the application you want the lender to see.
7. The guarantor question, handled honestly
A guarantor can strengthen a weak application, and the guarantee is a real promise against real security. Both parties should get independent advice before anything is signed, and both should understand what happens if the loan stops being paid. This is the step to slow down, not the step to rush.
If the answer is no
A decline is information, not a verdict. Ask the lender for the reason, and ask for the credit report they used. Then fix what the file shows, wait a little, and apply somewhere the fit is better. Applying again immediately, to everyone, is how a difficult file becomes a difficult year.
A file you can explain
The goal is not a perfect file. It is a file that adds up: a report without surprises, debts moving in the right direction, a deposit that grew on purpose, and papers that arrive before they are asked for. Do the seven steps in order and the application does its own talking. And if you start today, the whole thing fits comfortably inside the month.
Sources: the three Australian credit reporting bodies, Equifax (equifax.com.au), Experian (experian.com.au) and Illion (illion.com.au), publish how to obtain your free credit report and how to correct it; the Australian Securities and Investments Commission (moneysmart.gov.au) publishes guidance on car loans and comparison rates.

Extended Warranties Mostly Sell You Rights the Consumer Guarantees Give Free

Payday Super Gives Your Employer 7 Business Days. Check Your Fund on Day 10

Heat Exhaustion or Heatstroke? The Signs That Turn a Hot Day Into a 000 Call


 Healthcare1 year ago
SIL Providers: What to Compare Before You Commit
- Healthcare1 year ago
What Is Physiotherapy?
- Healthcare1 year ago
What a Dental Implant Replacement Costs in Melbourne
- Food1 year ago
Budget Bites: Delicious Meals You Can Cook for Under $10
- Healthcare1 year ago
What Changes When You Start SIL
- Tech1 year ago
Mental Health Apps and Wearables: What to Trust
- Home & Garden1 year ago
Gutter Upgrades Worth Doing Before You Sell
- Healthcare1 year ago
How to Put NDIS Community Participation Funding to Work





You must be logged in to post a comment Login