Travel
The Japan Rail Pass After the Price Rise: Price the Trip Before You Buy the Pass

The platform at Tokyo Station hums in the way only a big railway station can, a low layer of announcements and wheeled suitcases and the soft chime before each departure. Halfway along it, a woman from Brisbane stands with a folded sheet of paper in one hand and a takeaway coffee going cold in the other. On the paper, in her own handwriting, is the trip: Tokyo, then Kyoto, then Osaka, then home. Beside each line she has written a number with a question mark after it.
She is doing the sum that every first-time visitor to Japan seems to do somewhere between booking the flights and boarding the first train. The pass, or the tickets? Her friends told her the Japan Rail Pass was the obvious thing to buy. The internet told her it was dead. The truth, as she is about to find out, sits on that sheet of paper, and it depends almost entirely on the lines she has written down.
The Japan Rail Pass is neither a bargain nor a trap by nature. It is one fixed price for JR travel over a set number of days, and whether it pays depends on how far you go inside those days. Since 1 October 2026 it also depends on where you buy it.
What the pass costs now
The official JAPAN RAIL PASS site, run for the JR Group, now lists two prices for every pass: one for buying online through the official site, and a higher one for buying through an overseas JR-designated agency. These are the prices it shows, in yen:
| Pass | Bought online (official site) | Bought through an overseas agency |
|---|---|---|
| Ordinary, 7 days | 50,000 | 53,000 |
| Ordinary, 14 days | 80,000 | 84,000 |
| Ordinary, 21 days | 100,000 | 105,000 |
| Green, 7 days | 70,000 | 74,000 |
| Green, 14 days | 110,000 | 116,000 |
| Green, 21 days | 140,000 | 147,000 |
Children aged 6 to 11 pay half.
The gap between the two columns is small next to the price of the pass itself, but it is real money. On a 7-day Ordinary pass it is 3,000 yen. On a 21-day Green pass it is 7,000 yen. For a family of four, the difference adds up quickly.
What changed on 1 October 2026
The JR Group announced the increase on 9 April, and it took effect on 1 October 2026. The Japan National Tourism Organization (JNTO) explains how it lands: passes bought through overseas agencies now carry the higher price, while booking through the official site keeps the pre-October prices for a limited time. JNTO says the length of that window will be announced.
So the rise is real, and for now it is avoidable. The online column in the table above is the old price held in place. The agency column is the new one.
That “for now” matters. The official site has not said how long the online price will hold, and a traveller who reads this article in a few months may find the two columns have closed. The only reliable price is the one on the official site on the day you buy, so check it then, not when you first start planning.
Travellers who remember the pass from years ago still talk about it the way people talk about a café that used to be cheap, and in their telling this is not the first rise. In one long discussion of the October rise, a commenter wrote that the pass “does not make sense for 95% of tourists who only visit Tokyo, Kyoto, Osaka and Hiroshima”. Another suggested the JR Group was raising the price “to effectively kill the pass, without officially killing the pass”. Those are opinions, and strong ones. What they point at is worth taking seriously, though: for a lot of itineraries the pass stopped being an automatic win some time ago.
The sum
Back on the platform, the woman from Brisbane is filling in her question marks. This is the part that decides everything, and it is simpler than the arguments online make it sound.
Step 1. List every long-distance journey. Not the city trains, not the subway to the museum. The intercity legs: the Shinkansen from one city to the next, the limited express to the hot spring town, the day trip that runs two hours each way.
Step 2. Price each one as a single ticket. Use JR’s own fare information for each leg, for the class of seat you would actually buy. Write each fare beside its journey.
Step 3. Add them up. That total is what the trip costs without a pass.
Step 4. Compare it with the right pass. Pick the duration that covers your long journeys, not your whole holiday. If the long legs all fall within 7 days, the 7-day pass is the comparison, even if you are in Japan for three weeks.
On paper, it looks like this:
| Journey | Single fare (yen) |
|---|---|
| Leg 1: ______ to ______ | ______ |
| Leg 2: ______ to ______ | ______ |
| Leg 3: ______ to ______ | ______ |
| Leg 4: ______ to ______ | ______ |
| Total of single tickets | ______ |
| Pass for the matching duration | ______ |
If the total is higher than the pass, the pass is worth looking at. If it is lower, the pass is costing you money, and the convenience of not buying tickets is the only thing it still offers. For some travellers that convenience is worth the difference. It should be a choice made knowingly, though, not a default.
The traveller on the platform is planning a Tokyo, Kyoto, Osaka loop with no long side trips, which is exactly the trip the forum comment had in mind. When she adds her line, the question marks start to come out lower than the pass.
The Nozomi catch
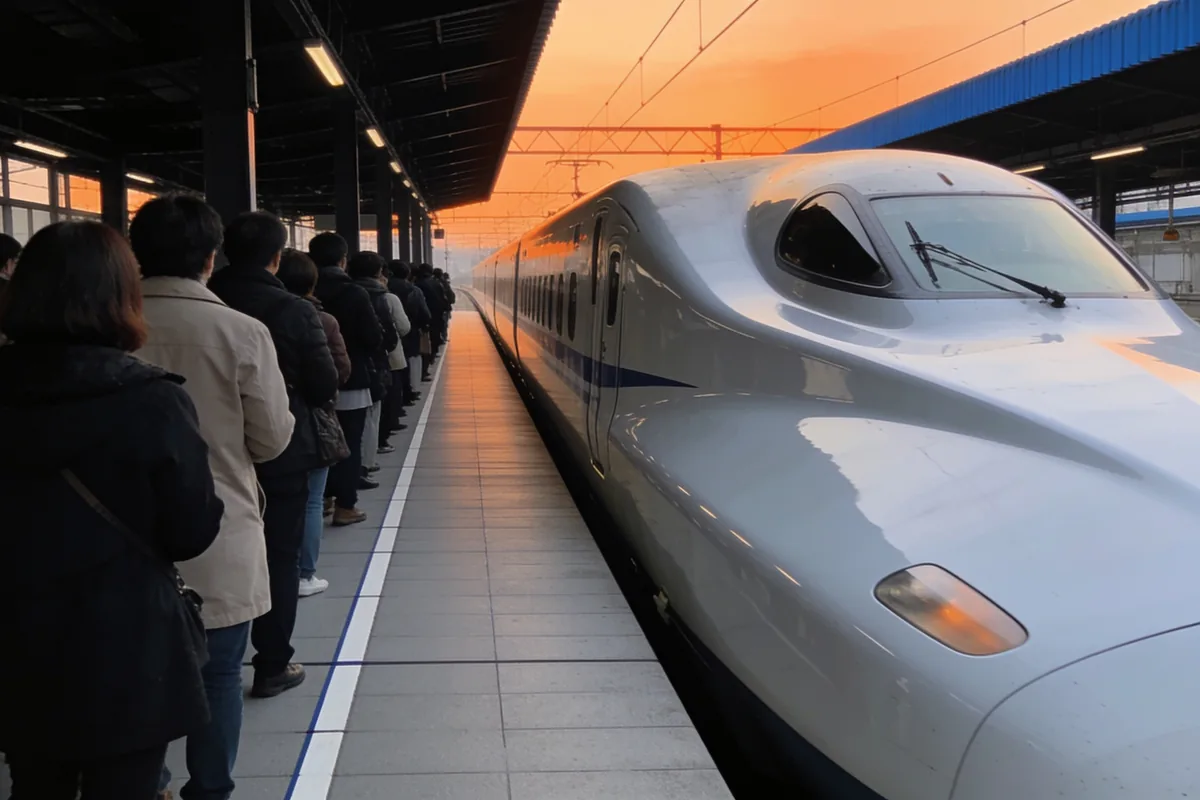
There is one more line her friends did not mention, and it sits right on the Tokyo to Osaka corridor.
The fastest services on the Tokaido, Sanyo and Kyushu Shinkansen lines are the NOZOMI and MIZUHO trains. According to the official pass site, pass holders cannot simply board them on the pass. They need an extra special ticket, which can only be issued to pass holders, on top of the pass itself.
That changes the sum in a specific way. If you would naturally ride a NOZOMI between Tokyo and Kyoto, your single-ticket comparison should include what that journey costs on that train, and your pass column should include the pass plus the special ticket. Comparing a single NOZOMI fare against a bare pass flatters the pass. Comparing the right pair of numbers is the only fair test.
The alternative is to ride the slower services the pass covers without the extra ticket and accept a longer journey. Some travellers are happy to. Others, with a short trip and a long list, are not. Either way, decide before you buy, because the choice changes which column wins.
Where the pass still earns it
The pass is not dead, whatever the videos say. Its job has narrowed.
It earns its price when the long journeys are long and many, and when they are packed into a short window. A traveller who will cover several regions in a single week, with a long Shinkansen ride most days, is the traveller the pass still suits. So is someone who would otherwise buy several long tickets inside 7 days and wants the freedom to change plans without rebooking.
The more of your journeys that are short, the fewer that are inside the pass window, and the more of them that are on NOZOMI or MIZUHO services, the weaker the case becomes. Put plainly, the pass rewards distance and density. A slow, deep trip through two cities rarely gives it either.
One traveller summed up the other side in a post about using the 7-day pass and finding it worth it “for a certain demographic”. That is fair. The demographic is people whose sum comes out in the pass’s favour. There is no shortcut to knowing whether you are in it except doing the sum.
The other options to price
If the sum goes against the pass, there are other ways to pay for the same trains, and they are worth pricing the same way.
Single tickets. The obvious one. You have already priced them in the table.
Regional JR passes. Several regions have their own JR passes covering a smaller area. If your trip stays within one region, a regional pass may fit better than the nationwide one. Price it against your legs exactly as you priced the nationwide pass.
Pay-as-you-go IC cards. For city travel, the trains and subways you take between sights, a pay-as-you-go IC card is the category to look at. Keep those short fares out of your long-distance sum and price them separately, so neither total hides the other.
Each of these is a category to check, not an answer. Coverage and prices change, so look them up on the operator’s own site when you plan, the same day you check the pass.
Add up the tickets first
On the platform, the woman from Brisbane folds her sheet of paper and puts it in her pocket. Her total of single tickets has come out under the 7-day pass, so she buys her next ticket at the machine and boards a train she chose herself. Her friends will still tell her the pass was the obvious buy. For their trip, maybe it was.
For yours, the order is simple. Write down every long journey. Price each one as a single ticket from JR’s own fares. Add them. Compare the total with the pass for the matching number of days, add the NOZOMI special ticket if you will ride those trains, and check the official site’s online price on the day you buy, because the gap with the agency price may not last.
While you are sorting the trip, the rest of the admin is worth the same care. Before you lock anything in, read through the travel insurance exclusions that catch people out, so the policy fits the trip you are actually taking.
Then buy whichever column wins.
Sources: Types and prices, JAPAN RAIL PASS official site, JR Group (https://japanrailpass.net/en/purchase/price/); Price Increases are Coming to the Nationwide Japan Rail Pass (2026), Japan National Tourism Organization (https://www.japan.travel/en/ca/news/price-increases-are-coming-to-the-nationwide-japan-rail-pass-2026/)


A travel policy is its exclusions. The cover is the advertising, the price is the comparison, and the exclusions are the contract. When a claim is refused, the refusal almost never arrives as a surprise to the insurer; it arrives as a surprise to the traveller, who is meeting the deciding clause for the first time after the event it governs.
That disputes are routine rather than rare is measurable. Travel insurance sits among the top five general insurance products in complaints to the Australian Financial Complaints Authority, at about 2,477 complaints in the authority’s most recent year-at-a-glance figures. The volume matters for one reason: it means the outcomes have been tested, published and, in some cases, corrected. The clauses that decide claims are knowable, and this article walks them in the order that disputes tend to reach them.
The reframe is worth one step further, because it changes what a purchase looks like. Comparing two policies on price and headline limits compares their advertising against each other; comparing them on exclusions compares their contracts. A traveller who does the second comparison sometimes buys the policy that looked worse on the sales page, for the entirely rational reason that it covers the thing they fear: a medical event far from home, a wedding that cannot go ahead, a bag that never arrives.
How a claim is decided
The procedural point is the most useful one in this subject, and it is the one travellers hear least. Under the contract and the framework of the Insurance Contracts Act 1984, an insurer that refuses a claim on the basis of an exclusion carries the onus of establishing that the exclusion applies. It must identify the clause, show that the circumstances fall within it, and address the Act where the Act bears on the reading. A refusal without a clause is not a decision; it is an assertion, and it can be pressed.
Which is why the most common sentence in refused-claim stories, some version of “I never saw that in the policy”, is both true and beside the point. The traveller never saw the clause because nobody reads a product disclosure statement front to back on the way to the airport. The insurer, by contrast, reads its clauses professionally. The asymmetry is the whole game, and the remedy is not to read the entire document. It is to know which families of clauses decide claims, and to check yours against them before the money is spent.
For the traveller, one practical habit follows from the onus rule: ask for a refusal in writing, clause and all, and keep the correspondence. A decision reduced to a clause can be tested against the clause. One left as a conversation on a phone line cannot be tested against anything.
The same discipline shows up wherever a document governs a purchase, and the site has covered it on other paper: logbook servicing and the fine print of a warranty is the same exercise in a different industry, where the conditions that void the cover sit in sentences nobody reads until they matter. Travel insurance is that lesson with a passport.
The clauses that decide most claims
Five families of clause carry the bulk of disputes, and each has a characteristic shape that can be checked against a policy in minutes. The examples below are drawn from the published determinations of the complaints authority, described without the parties, because the pattern is what matters rather than the case.
Medical cover and pre-existing conditions come first, because they carry the largest sums and the strictest tests. A condition that showed signs or symptoms before cover began, or during the policy’s waiting period, is generally treated as pre-existing, and the definitions of “signs” and “symptoms” are deliberately wider than a diagnosis. One recurring dispute concerns age: several policies limit medical cover for travellers past a certain age unless a higher tier is purchased, and a claim from a traveller over 80 without the required upgrade meets its clause rather than its merits.
One habit helps with all five families: the policy schedule, not the product disclosure statement prose, is where the limits live. The schedule is the short table that lists each section, its limit and its excess, and it can be read in minutes. The prose explains; the schedule decides. A traveller who reads only one of the two should read the table.
Cancellation is the second family, and its trap is the closed list. Many policies cover cancellation for a list of specified events rather than for any good reason, and a reason that is not on the list is not covered, however sound it was. The determinations include a traveller detained by authorities over a souvenir knife who argued that detention should count as an event; the policy’s list did not include detention, and the claim met the list rather than the argument. The lesson generalises: with cancellation cover, read the list, and if your reason is not on it, do not assume a good story will carry the day.
Delay thresholds form the third family, and they are the least dramatic and the most frequently missed. Where a policy covers travel delay or missed connections, the cover usually begins only after the delay passes a stated threshold, and the threshold is expressed in hours rather than days. A delay shorter than the policy’s number produces no claim, however disruptive the night that followed it. The number is worth finding in advance, because it also tells the traveller what receipts to keep: below the threshold, the expense is simply theirs.
War, unrest and official advice make up the fourth family, and it has grown teeth. Policies commonly exclude loss connected with war, invasion, civil unrest and similar events, and some extend the exclusion to destinations the government advises against travelling to. This clause turns a destination question into a pre-purchase question: the time to check how a policy treats a region is while the booking is being paid for, not while the news from that region is worsening.
Activities and theft complete the set. Adventure activities are excluded unless the policy extends cover to them, and the list of what counts as adventure is broader than most travellers expect, extending to things as unremarkable as riding a scooter in some policies. Theft cover, meanwhile, comes with reporting conditions: a police report within a stated window, receipts for the items, and sometimes proof of how they were secured. A theft claim that misses the reporting condition is refused on the condition rather than the theft.
What almost everyone gets wrong
Two confusions account for a large share of disappointed travellers, and both come from treating a policy as a single promise rather than a shelf of separate ones.
The first is the difference between emergency medical cover and travel costs. These are different clauses with different limits, and a policy can be generous on one and narrow on the other. Emergency medical cover addresses treatment and evacuation under the policy’s terms. The costs of a disrupted trip, the extra nights and changed flights, sit under different sections, often with their own caps and their own conditions. A claim that reads “but I was covered for medical” is answered by a schedule that never promised the other thing.
The second is “I am covered anywhere”. A policy is written against a trip, not against a person. The destination, the dates, the activities and the length of the journey are all variables the cover is priced around, and each of them appears inside conditions in the document. Extend a trip, change a destination, add a leg on the ground, and the conditions that were satisfied at purchase may not be satisfied at the claim. What the policy excludes, in this as in everything, is the part where the facts changed and nobody told the insurer.
The Australian facts worth knowing
Three facts particular to Australian travellers are worth carrying into the purchase, because each one changes how much a policy is protecting in practice.
The first is timing. The government’s travel advice service recommends buying insurance when the trip is booked rather than when it is about to begin, and the reason is mechanical: cancellation cover cannot protect a booking made before the policy existed. A policy purchased the week before departure has quietly excluded the risk that most often materialises before departure.
The second is that the Australian Government does not pay a traveller’s medical bills or evacuation costs overseas. Consular assistance helps with processes; it is not insurance. The third is the nature of reciprocal health agreements: Australia holds arrangements with some countries that cover some treatments, often under conditions and generally not the costs of returning home. A reciprocal agreement is a helpful fact and a poor substitute for a policy, and the difference between the two is worth understanding before it is needed.
When a claim goes wrong
The recourse is real, and it is free. A traveller whose claim is refused can complain to the insurer first, and if the outcome remains unsatisfactory, take the matter to the Australian Financial Complaints Authority, which handles disputes about general insurance at no cost to the complainant. The authority’s jurisdiction, procedures and timeframes are published, and its decisions are made against the same clauses this article has walked, which is why its determinations read like a syllabus in policy interpretation.
The authority also corrects insurers when policy interpretation itself has gone wrong, and the clearest example is systemic. In one decision, it was found that a condition requiring both trips to be purchased on a linked credit card had been applied by an insurer to refuse claims, and the ruling overturned 24 previous denials built on the same reading. One decision, in other words, did not merely settle a dispute; it corrected a pattern. That is worth knowing before accepting a refusal as final.
The order of complaint is short enough to state in full. Raise the dispute with the insurer’s internal process first and keep the reference number. If the answer stands and the dispute remains, the authority takes it from there, at no cost to the complainant, and decides it against the policy and the law rather than against the marketing. Nothing in that path requires a lawyer, and nothing in it requires fluency in the document. It requires the correspondence and a plain account of what happened.
The clause to read first
The practical close is a short set of questions, and none of them requires reading the whole document. Ask the policy, not the sales page, about each of these before the money moves.
- Pre-existing conditions: what counts, when the clock starts, and whether any upgrade is required for age or health.
- Cancellation events: find the list, and check that your reasons for travel would appear on it.
- The delay threshold: the number, in hours, at which delay cover begins, and what it covers once it does.
- Activities: whether the things you plan to do are covered by name, or excluded by omission.
- Reporting conditions: the windows and evidence required for a theft or loss claim, noted before the trip rather than after one.
One habit ties the list together, and it follows the pattern set by the site’s own booking advice in wedding car hire and the decisions before the big day: settle the conditions that decide the money before paying the deposit, not after the event has tested them. Travel insurance simply raises the stakes on the same discipline.
The clause to read first, if only one is read, is the exclusions section, because it decides everything the rest advertises. The second is the list of cancellation events. Between them, they hold the answers to most of the disputes that reach the ombudsman, and meeting them at the kitchen table costs an evening. Meeting them at the claims stage costs the trip.
Sources: Australian Financial Complaints Authority – year-at-a-glance complaint figures and published determinations on travel insurance; Smartraveller – travel insurance advice (Department of Foreign Affairs and Trade); Insurance Contracts Act 1984 (Cth), cited as the framework applied to claims.

You have the date, the venue and the people you love. The car is a smaller booking than any of those, and it can be settled in an afternoon. Before a deposit changes hands, these are the things worth deciding.
What you are booking
A wedding car booking is not just a car. It is a car, a driver and a window of time on a day when the schedule is tight. The car gets all the attention, and the other two decide whether the morning runs smoothly.
Read the inclusions with that in mind. Ribbons and decor, photo stops, the hour the hire starts and ends, and how far the car will travel are all line items, and they differ between operators. So does the second trip: plenty of couples use one car for one leg and something else for the rest, and that plan only works when someone has written down who travels where, and when.
The two-seat problem
Most of the cars people picture for a grand entrance seat two: a driver and one passenger. That is fine. It just changes the logistics, because if you are both travelling, you are not travelling together, at least not in that car. Decide who rides when, and who travels with whom, before the day rather than in the driveway.
Practise getting in and out once, in the dress or the suit. Low seats and long trains are a combination that photographs badly when it surprises people. One dry run at the fitting settles it, and it makes a lovely photo of its own.
The getting-ready hour
Most cars arrive before the ceremony, sometimes well before, because the photographs start when the dress is on. That hour is where timelines go wrong. Hair runs over, and the car sits outside while the morning catches up. Give the operator the time you will really be ready rather than the time you hope to be, and let the photos have their place in the plan rather than being discovered on the day.
Choose the car for the photos you want
The car appears in two kinds of photo: the arrival, and the portrait session around the corner. Colour, the shape of the doors and the backdrop of the venue do more for those photos than any badge on the bonnet. On a busy Saturday in spring, traffic anywhere in the city takes longer than anyone plans for, so build a buffer into every leg, and let the photographer have their ten minutes with the car before it is waved away.
How far ahead to book
Popular cars and popular dates go first, and the two together go first of all. A weekday wedding in winter has room to move. One specific car on a Saturday in spring is a booking to make early rather than eventually. Decide how attached you are to the exact model, and if the answer is very, start looking sooner than feels necessary. The calendar does not mind either way, but the good cars fill.
What moves the price
The car itself is one variable. The others are the length of the hire, the distance travelled, the day of the week, and what is included in the figure. That is why two quotes can look far apart while describing different things. Compare them on the same schedule, with the same inclusions, and the real difference usually shrinks to something you can judge. Then choose on the condition of the car, the terms and the driver, because those are the parts a lower price rarely improves.
What to ask before you pay the deposit
- Is the exact car guaranteed? Some operators write “this car or similar”. That is a reasonable sentence and a real difference on the day, so know which one applies before you pay.
- What is included? Hours, distance, ribbons, photo stops and the second trip. Get the inclusions in writing rather than in a phone call everyone remembers differently.
- What happens if the car cannot attend? Breakdowns happen. A careful operator has a backup plan and describes it plainly when asked.
- What are the cancellation and weather terms? Postponements, rain and date changes each have conditions. Read them while the date is still far away.
- What deposit is held, and when does it come back? Know whether it is a booking deposit or a security bond, and what could see it kept.
- Who drives? For this kind of hire, the answer should be the operator’s professional driver, with the insurance and experience that come with the role.
The day itself
Give the driver the schedule, and give the same schedule to whoever is keeping the day on track. Drivers do this every weekend. They are calm, and they are used to wedding time. A driver who knows the plan does not need managing, and one who has to chase the plan cannot do their best work. If there is a stop you are hoping for that is not on the sheet, say so before the day rather than from the back seat.
The person behind the wheel is working a job like any other that day, and the habits that make a driving job good are the same in every kind of car. What separates a smooth trip from a rushed one is worth a read if you want to know exactly what you are paying for.
The car is one booking, not the whole day
Decide the few things that matter to you, put the rest in the operator’s hands, and keep the morning’s list short. The best wedding car moment is the one you did not have to manage.
Sources: consumer affairs agencies in each state and territory publish guidance on vehicle hire agreements, deposits and cancellations; the operator’s written terms are the document that governs the booking.


 Healthcare1 year ago
SIL Providers: What to Compare Before You Commit
- Healthcare1 year ago
What Is Physiotherapy?
- Healthcare1 year ago
What a Dental Implant Replacement Costs in Melbourne
- Food1 year ago
Budget Bites: Delicious Meals You Can Cook for Under $10
- Healthcare1 year ago
What Changes When You Start SIL
- Tech1 year ago
Mental Health Apps and Wearables: What to Trust
- Home & Garden1 year ago
Gutter Upgrades Worth Doing Before You Sell
- Healthcare1 year ago
How to Put NDIS Community Participation Funding to Work





You must be logged in to post a comment Login